

Solar Firms Build BESS Capacity for Next Growth Phase: Interview
Solarworld has commissioned a 3.6 GWh BESS manufacturing facility at Roorkee, Uttarakhand
October 1, 2026

Follow Mercom India on WhatsApp for exclusive updates on clean energy news and insights
As energy storage becomes increasingly important to renewable energy integration, solar companies are positioning themselves for the next phase of growth by building battery energy storage system (BESS) manufacturing capabilities.
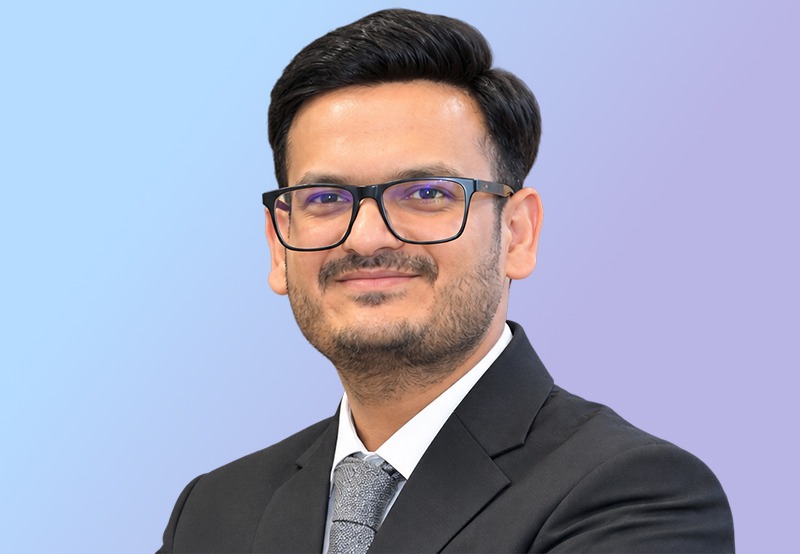
In an exclusive interview with Mercom India, Kartik Teltia, Managing Director at Solarworld Energy Solutions, discussed the growing role of energy storage, the dominance of TOPCon solar module technology, and the need for upstream manufacturing capabilities.
What is Solarworld’s current solar module manufacturing capacity, and what are the company’s expansion plans for solar cell and module production?
Our ALMM-listed module manufacturing facility in Roorkee, Uttarakhand, has a capacity of 1.55 GW and uses N-Type TOPCon technology. This gives us a strong base to serve both our own EPC pipeline and the wider market as India scales solar manufacturing.
We have entered into a joint venture with Rays Power Infra to set up a 2.4 GW solar cell manufacturing facility in Narmadapuram, Madhya Pradesh, with commercial production targeted for June 2027.
Once operational, this will allow us to supply modules with domestically manufactured cells rather than relying on imports.
Which solar module technologies is Solarworld prioritizing? How do you expect the TOPCon, HJT, and larger wafer format technologies to evolve in India?
At Solarworld, our modules are built on N-Type TOPCon, currently the technology of choice across the industry. Recent industry data shows TOPCon accounted for close to 40 GW of the roughly 44 GW of new module capacity India added in the first half of this year. In contrast, HJT capacity was added for the first time at a much smaller scale, at around 1 GW.
I expect that gap to persist for the next few years. TOPCon has reached a point where the supply chain, equipment, and cost curve are all mature, whereas HJT still carries higher capital costs and a thinner domestic ecosystem.
On wafer formats, the industry has largely settled on the larger M10R and G12R formats, which we also use, since they improve output per module and reduce balance-of-system costs for developers.
HJT will likely find its place in premium or space-constrained applications rather than replacing TOPCon at utility scale in the near term. Our own investment plans, including the upcoming cell facility, are built around this TOPCon-led trajectory.
Project developers often raise concerns about module reliability, including micro-cracks and long-term degradation. What manufacturing and quality-control measures does Solarworld use to address these concerns?
At Solarworld, we build reliability into the manufacturing process itself, rather than checking for it only at the end of the line. Our facility uses automated production processes, reducing manual handling and inconsistent thermal exposure that can contribute to micro-cracks and soldering-related defects in solar modules.
Every module we manufacture goes through extended reliability testing and compliance checks against the requirements of the Bureau of Indian Standards (BIS), the International Electrotechnical Commission (IEC), and the ALMM before it leaves our Roorkee facility.
This layered testing approach is designed to identify defects, whether cosmetic or structural, well before a module reaches a project site. Our experience with large-scale EPC projects also shapes how we manufacture and test our modules.
Energy storage is becoming increasingly important for grid stability. Solarworld has commissioned an automated 3.6 GW BESS manufacturing line. What is the engineering architecture of this facility, and how is the company positioning its storage solutions in the market?
Energy storage is becoming a critical part of the renewable energy ecosystem. India’s storage requirement is projected to grow several times over by the early 2030s as renewable capacity scales and grid stability needs increase. We see BESS manufacturing as a natural extension of our solar manufacturing base and existing utility relationships.
We have commissioned a fully automated 3.6 GWh BESS manufacturing facility at Roorkee, built with KUKA robotics across the production line to ensure consistency at scale. The facility is designed around a liquid-cooled architecture for both our commercial and industrial units and larger containerized systems, as thermal management is critical to battery life and safety at grid scale.
India is rapidly expanding domestic solar manufacturing, but upstream segments such as wafers and ingots are heavily import-dependent. How should the industry prepare for the possibility of ALMM requirements extending further upstream?
MNRE has extended the ALMM framework to cells from June 2026, and further upstream to ingots and wafers under a new List III from June 2028, with conditions requiring at least three independent manufacturers with a combined manufacturing capacity of 15 GW before the list can be issued.
The policy direction is clear, and companies need to plan their investment cycles accordingly rather than wait. Wafers and ingots are capital-intensive and still almost entirely import-dependent in India, so the runway before 2028 needs to be used effectively.
At Solarworld, we will evaluate wafer and ingot integration as the domestic ecosystem matures.
The industry must prioritize building a domestic wafer and ingot supply base with meaningful operating scale rather than relying solely on announced capacity.
How does the current inverted duty structure and GST framework affect domestic manufacturers and EPC companies? What policy changes would help create a more competitive domestic manufacturing ecosystem?
The inverted duty structure remains a working-capital challenge for both domestic manufacturers and engineering, procurement and construction (EPC) companies.
The accumulated input tax credit locks up capital that could otherwise support capacity expansion, technology adoption, and faster project execution.
Rationalizing GST rates on key inputs to bring them closer to those applicable to finished systems would improve cash-flow efficiency and reduce friction for domestic manufacturers and EPC companies.
Solarworld has a portfolio of more than 1.5 GW of solar EPC projects across India. What are the key operational challenges in developing and executing large-scale utility projects today, and how does backward integration give the company an advantage?
Land acquisition and aggregation remain recurring hurdles, especially for large utility-scale sites involving multiple parcels and approvals. Grid evacuation and transmission readiness are other challenges, as project timelines are increasingly tied to how quickly connectivity infrastructure catches up with generation capacity.
By developing our upstream supply chain, we have gained greater control over the quality and availability of the components going into our projects, rather than depending entirely on external suppliers during periods of tight supply or price volatility.
What is your outlook for 2030 in India’s clean energy transition?
By 2030, we expect Solarworld to be a fully integrated renewable energy company across solar modules, solar cells, EPC, and battery storage systems manufacturing.
India is expected to add close to 345 GW of renewable capacity between 2025 and 2030, with utility-scale solar accounting for the largest share of that growth, while storage will increasingly complement renewable energy as the grid absorbs more variable generation.
We want to be positioned at multiple points along that value chain. Our cell manufacturing facility is targeted to begin commercial production soon, and our BESS manufacturing business is built with that horizon in mind.
This interview was sponsored by Solarworld Energy Solutions.

Melvin Mathew
More articles from Melvin Mathew.