

Rising Raw Material Costs are Squeezing Solar EPC Margins: Interview
Domestic manufacturing policies will strengthen the solar supply chain, but short-term price volatility and technology curbs remain challenges
November 11, 2026

Follow Mercom India on WhatsApp for exclusive updates on clean energy news and insights
Rising raw material prices, shrinking module manufacturing margins, and fixed-price contracts are challenging India’s solar engineering, procurement, and construction (EPC) companies. At the same time, domestic manufacturing policies, global trade restrictions, and the increasing adoption of battery energy storage systems are reshaping the industry’s growth prospects.
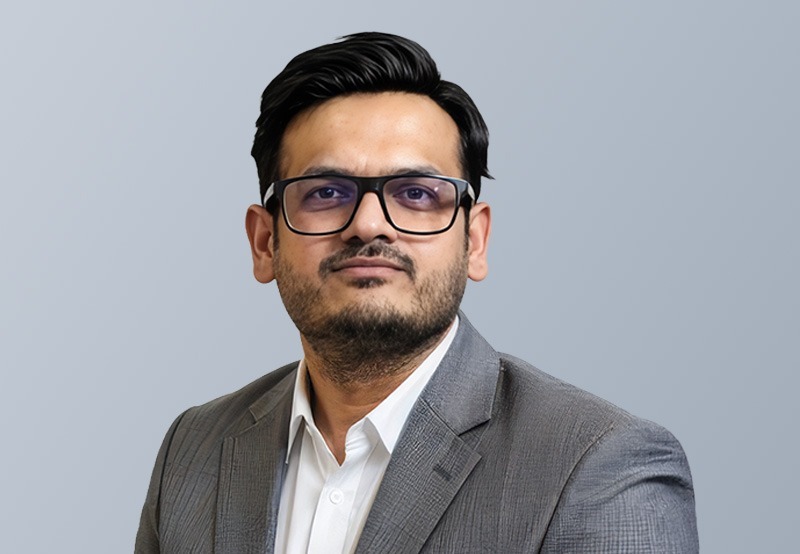
In an interview with Mercom India at the recently concluded Renewable Energy India (REI) Expo 2026, Kartik Teltia, Chairman and Managing Director at Solarworld Energy Solutions, discussed the challenges solar EPC companies face, the impact of the Approved List of Models and Manufacturers (ALMM) framework, China’s proposed restrictions on solar manufacturing technology exports, and the growing importance of battery storage.
What are the biggest challenges that solar EPC companies face in India? Are transmission connectivity and land acquisition the primary concerns?
At Solarworld, we primarily target projects where land acquisition is complete because those projects are more likely to be executed.
However, the biggest challenge for EPC companies is fixed-price contracts. Most contracts are awarded at a fixed price and typically have execution periods of 14 to 18 months.
When metal prices are rising sharply, maintaining margins becomes extremely difficult. EPC companies must find ways to hedge raw material costs.
Transmission connectivity is a challenge, but one that’s generally manageable. It may increase project costs, but projects can still proceed.
How are fluctuations in module prices, balance-of-system costs, and raw material prices affecting EPC margins?
Since December last year, raw material prices have increased significantly. Copper prices have reached record highs, aluminum prices have also risen sharply before moderating, and zinc continues to trade at elevated levels.
The impact is particularly severe for public sector undertaking contracts, which are generally fixed-price contracts. EPC companies cannot pass these additional costs on to customers, directly affecting their margins.
Solar module manufacturing capacity has expanded significantly in India. How is this affecting manufacturers’ margins?
Margins in solar module manufacturing have compressed considerably. Excluding raw material costs, module tolling charges, which include manufacturers’ margins, were previously around ₹1.50 (~$0.0159) to ₹2.50 (~$0.0265)/W. They have now declined to approximately ₹0.80 (~$0.0085)/W. This has significantly affected solar module manufacturers’ profitability.
I believe margins are gradually shifting from module manufacturing to solar cell manufacturing. Eventually, a greater share of the value will move further upstream to ingot and wafer manufacturing.
India has a significant gap between solar module and cell manufacturing capacity. Does domestic cell capacity need to catch up with module capacity?
I do not think India’s solar cell manufacturing capacity necessarily needs to match its module manufacturing capacity.
With the customs duties imposed on Indian solar products entering the U.S., domestically manufactured cells will predominantly serve the Indian market. If India is installing approximately 50 GW to 60 GW of solar capacity annually, it does not necessarily need 200 GW of domestic cell manufacturing capacity.
How will U.S. antidumping and countervailing duties affect Indian solar manufacturers and their export opportunities?
The U.S. is following a strategy similar to what India adopted earlier by imposing duties to encourage domestic manufacturing. As a result, Indian manufacturers are increasingly looking at establishing manufacturing facilities in the U.S. to serve that market.
For manufacturing capacity located in India, the domestic market will remain important. Companies will also explore export opportunities in Europe and Africa.
China has proposed restrictions on exports of solar manufacturing technologies. What implications could these have for India’s manufacturing expansion?
Solar manufacturing equipment is sourced primarily from China and Europe. At Solarworld, we have placed equipment orders with a German supplier, which helps reduce our exposure to potential restrictions on Chinese equipment exports.
For companies sourcing equipment from China, export approvals and the final regulatory framework will determine how easily they can procure the required machinery and technology.
Alternative suppliers are available, including in Southeast Asia, but manufacturers may need to change their sourcing strategies. The challenge grows as companies move upstream into solar cells, ingots, wafers, and polysilicon.
Solar cell manufacturing is much more capital-intensive than module manufacturing. Ingot and wafer production require further investment, while polysilicon manufacturing is particularly complex and expensive.
What challenges do EPC companies face in ensuring construction quality and the long-term performance of solar projects?
Construction quality in India has improved significantly over the years. However, one major challenge is the lack of accurate ground-level solar irradiation data.
India has not invested sufficiently in establishing monitoring stations to record irradiation data accurately across different locations. As a result, irradiation levels assumed during project planning can differ significantly from the actual irradiation recorded after commissioning.
How will the ALMM framework and import duties affect India’s solar industry in the long term?
From a long-term perspective, developing domestic manufacturing capabilities and reducing import dependence is important. However, short-term challenges remain.
For example, domestic solar module prices increased from approximately ₹21 (~$0.222)/W to ₹26 (~$0.0275)/W in June. Such increases can create difficulties for developers and EPC companies.
Hopefully, as additional domestic manufacturing capacity becomes operational, these fluctuations will moderate. At the same time, manufacturers must be allowed to earn reasonable margins.
How will the growing integration of BESS with renewable energy projects reshape the industry?
Two developments are taking place simultaneously. India’s electricity consumption is increasing, but demand growth is also becoming more variable. At times, the electricity system has surplus power, followed by periods of shortages.
Battery storage can help address this imbalance by storing surplus electricity generated during the day and supplying it during evening demand periods.
The government’s push to integrate battery storage with renewable energy projects is a positive development. However, storage also significantly changes project economics. For example, when a 100 MW solar project is paired with a large battery storage system, the storage component can cost almost as much as the solar project. This creates a major opportunity for EPC companies.
What are Solarworld’s plans for expanding its battery storage business over the next two to three years?
We are developing three categories of battery storage products. The first is containerized battery storage solutions with a capacity of 5 MW. The second is commercial and industrial (C&I) storage solutions ranging from approximately 100 kWh to 400 kWh. The third is residential battery storage solutions, which we have recently launched.
We are also evaluating backward integration into lithium-ion cell manufacturing. .
How do you assess the current adoption of battery energy storage in India, particularly among residential and commercial consumers?
Battery storage adoption is growing very rapidly across all three segments: utility-scale, C&I, and residential. In the residential segment, consumers increasingly recognize the advantages of lithium batteries over conventional lead-acid batteries.
Lead-acid batteries typically last about two to three years, whereas lithium batteries can last about 10 to 15 years, depending on usage. Lithium batteries also require considerably less maintenance.
C&I consumers are increasingly choosing lithium-based uninterruptible power supply systems for similar reasons. Another important development is that lithium battery prices are declining.
Although the initial investment in a lithium battery system may be higher, consumers are evaluating the total lifecycle cost. For example, if a lead-acid battery must be replaced multiple times over 12 years, the total expenditure can exceed that of a lithium battery system that lasts for most or all of that period.

Rakesh Ranjan
More articles from Rakesh Ranjan.