

India Adds 50.6 GW Solar Module and 9.7 GW Cell Manufacturing Capacity in 1H 2026
Top 10 manufacturers accounted for nearly 60% of module manufacturing capacity
September 24, 2026


Follow Mercom India on WhatsApp for exclusive updates on clean energy news and insights
India added 50.6 gigawatts (GW) of solar module and 9.7 GW of solar cell manufacturing capacity in the first half (1H) of 2026, according to Mercom India’s recently released research report, State of Solar PV Manufacturing in India 1H 2026.
Capacity additions in 1H were driven by the Approved List of Models and Manufacturers mandate and a strong solar project pipeline.
As of the report’s release, cumulative module capacity under ALMM List-I stood at 225.5 GW, while cumulative cell capacity under ALMM List-II stood at 35.5 GW.
As of June 2026, cumulative module manufacturing capacity in India stood at 261.7 GW, and cell capacity at 36.6 GW.
“Domestic cell shortages have become the biggest near-term challenge for India’s solar market. Module capacity has expanded rapidly, but cell supply has not kept pace, tightening availability and pushing up prices for compliant modules and sharply slowing project activity. Many module manufacturers are struggling to maintain production because of limited domestic cell availability. Installed cell capacity overstates actual availability, as new lines take months to reach stable commercial production. ALMM List-II has intensified the pressure by increasing dependence on domestic cell supply before enough capacity was commercially available,” said Raj Prabhu, CEO at Mercom Capital Group.
The top 10 manufacturers accounted for 60% of module capacity.
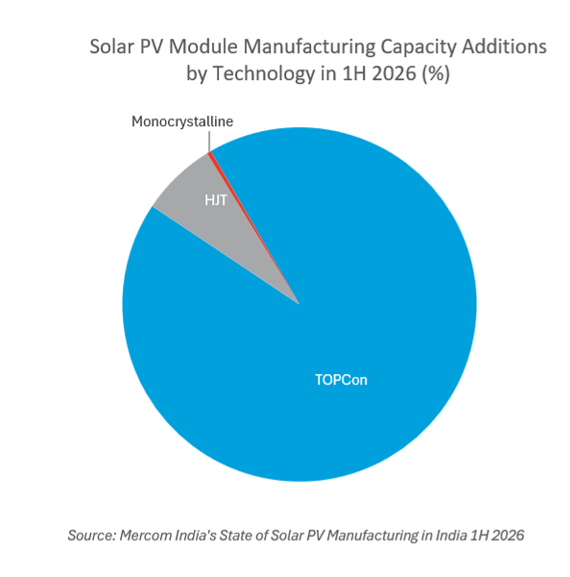
Tunnel Oxide Passivated Contact (TOPCon) accounted for the largest share of ALMM-listed module manufacturing capacity at 80% as of June 2026, followed by Mono PERC/TOPCon at 11% and Mono PERC at 4%.
HJT accounted for 3%, while thin-film technology represented 2% of the total ALMM-listed capacity.
“Until commercially available cell supply catches up with demand, the entire industry will remain under pressure, with manufacturers facing production constraints and developers facing commissioning delays,” added Prabhu.
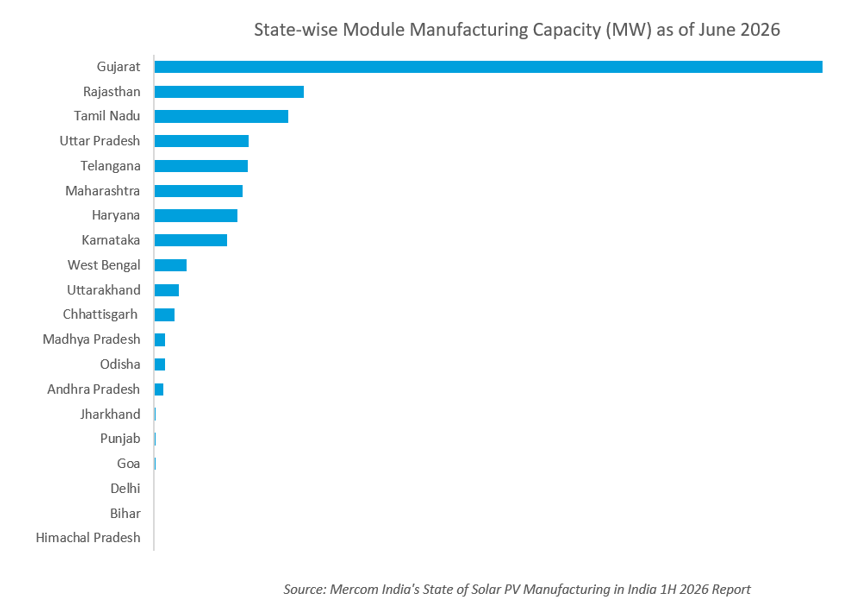
Gujarat remained the most favorable destination for solar module manufacturing production, accounting for nearly 45% of capacity as of June 2026. Rajasthan and Tamil Nadu followed with module production capacities of 26.1 GW and 23.4 GW, respectively.
Gujarat also held the largest annual solar cell production capacity at 37%. Tamil Nadu and Telangana were the other top states, with capacities of 4.3 GW and 4.2 GW, respectively.
In 1H 2026, India’s imports of solar cells and modules increased by 18% compared to 1H 2025. Cells accounted for 81% of total imports, while modules accounted for 19%.
Priya Sanjay, Managing Director at Mercom India, attributed the increase in solar cell imports partly to the extension of the ALMM-II compliance deadline for certain net metering and open access projects until December 31, 2026.
The U.S. remained India’s largest solar export destination in 1H 2026, accounting for 92% of total exports.
Mercom’s State of Solar PV Manufacturing in India 1H 2026 Report covers all facets of India’s solar PV manufacturing market, including demand and supply overview, top manufacturers, market outlook and projections, and manufacturing trends, among other details.
For the complete report, visit: https://www.mercomindia.com/product/state-solar-manufacturing-india-1h-2026

Melvin Mathew
More articles from Melvin Mathew.